Africa
CBN’s New Cash Policy: A Welcome Liberalisation or a Risky Retreat? -By Blaise Udunze
Nigeria is at an intersection. While cash can relieve hardships, it cannot shape the future economic landscape. The current task is to apply this policy without hindering progress, undermining financial integrity, or jeopardizing monetary stability.

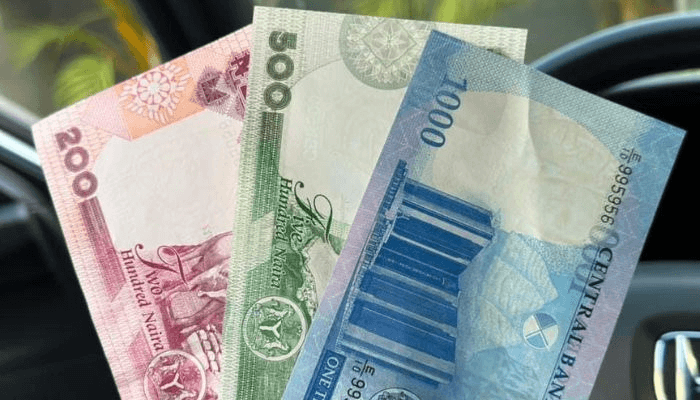
On December 2, 2025, the Central Bank of Nigeria (CBN) announced a policy that significantly departs from the cash-restriction measures Nigerians have faced lately. The apex bank abolished restrictions on cash deposits. Increased the weekly cash withdrawal limits to N500,000 for individuals and N5 million for corporates while substituting the earlier monthly limits of N5 million and N10 million respectively. These modifications, which will be effective from January 1, 2026, represent what the CBN describes as the necessity to “streamline provisions to reflect present-day realities.”
Authorized by the Director of Financial Policy & Regulation, Dr. Rita I. Sike, the policy overhaul aims to lower cash-management expenses, improve security, and lessen money-laundering threats related to Nigeria’s significant dependence on physical cash. Daily ATM withdrawal limits stay fixed at N100,000 and count toward the total cap. Withdrawals exceeding the limits incur charges of three percent for individuals and five percent for companies, with the revenues divided: 40 percent to the CBN and 60 percent to the banks.
This update comes three years following the disputed 2022-2023 cash redesign crisis at a time characterized by extreme cash deficits, extended lines at banks, and devastating impacts on the informal economy. Consequently, the newest order generates responses: praise from individuals who consider it delayed aid, disapproval from those perceiving it as a bewildering backtrack, and concern from those apprehensive about potential enduring hazards.
Experts Applaud a More Realistic Modification
For economists, in a publication by Nairametrics showed that the action taken by the CBN signifies much-needed practicality. Dr. Salisu Ahmed, an economist based in Abuja, refers to the updated limits as “a step,” praising the CBN for gaining a clearer insight into “cash management practices in a predominantly informal economy.”
He stated that the changes will alleviate the difficulties faced by families and small enterprises due to restrictions. Rigid withdrawal caps had limited transactions, made small-scale commerce more difficult, and caused numerous businesses to experience cash-flow problems. “This adjustment signifies a response from the CBN recognizing the challenges Nigerians face daily and easing rules that previously hindered commerce and individual management,” he clarified.
Banking analyst, David Omale, echoes this view, seeing the CBN’s action as a sign of responsiveness. He points out that higher limits could “enhance liquidity for firms facing challenges from inflation, supply-chain issues and unpredictable cash flows.”
In an economy in which over 60 percent of trade is informal and where the adoption of digital payments varies across different socio-economic groups, experts suggest the updated limits correspond more accurately to real-world conditions. These limits offer businesses flexibility to reinstate transactional liberty and may help recover public confidence diminished by previous cash shortages.
Critics Caution About Continuing Disparities and New Threats
However, the praise is not universally shared. Numerous specialists and industry participants contend that the modifications, although appreciated, are inadequate or might even be detrimental.
Financial strategist Nnenna Okafor contends that the updated limits are insufficient for traders and micro-businesses that depend largely on cash to sustain their operations amid challenges. Due to increasing product prices, logistical difficulties, and unreliable digital banking services in regions, she asserts that numerous Nigerians will still need more liquidity than the new thresholds to stay viable.
Within PoS operators’ players, in Nigeria’s payment system, the response is notably divided.
PoS Operators Split
Certain PoS agents appreciate the modifications, anticipating that they will:
– Reduce friction with banks over “flagged” transactions
– Facilitate processes for clients requiring withdrawals
– Rebuild trust after months of cash shortages
Others convey concern. A PoS operator in Lagos cautions that greater cash availability could hinder the adoption of payments. “While easier access to cash can address problems, it may also decrease dependence on PoS terminals and other digital payment solutions that provide long-term security and efficiency,” she remarked.
She argues that if the CBN does not combine the policy with targeted incentives to encourage payment uptake, Nigeria runs the risk of regressing into deep-rooted reliance on cash.
Another operator in Abuja points out a different issue that has to do with unstable cash supply at numerous commercial banks. He insists that simply boosting withdrawal limits does not automatically fix supply shortages. “If banks cannot consistently provide cash, raising limits fails to solve the issue,” he stated.
Other operators also caution that the new setting might push fintech firms out of the market, which possibly allows monopolies to form since only big payment firms can endure the transition back to increased cash usage.
Experts in Security Alert to Increasing Threats, from Crime
Apart from operational issues, security experts have expressed concerns about the dangers linked to greater cash flow.
Abas Ogendengbe, a security expert at Anold Consulting Ltd., warns that increased access to amounts without strict controls “opens up risks for theft, fraud and money laundering.” He contends that without improvements in surveillance transaction tracking and reporting frameworks by banks, criminal groups might take advantage of the restrictions.
Nigeria continues to confront:
– High rates of petty theft
– Organised criminal cash-for-goods networks
– Ransom-based criminality
– Fraudulent cash-flow manipulation
He contends that a policy boosting the amount of currency in circulation should consequently be accompanied by enhanced institutional protections, rather than diminished ones.
Advantages of the New Policy: Relief, Liquidity, and Business Freedom
Although it has faced criticism, the CBN’s decision carries benefits:
1. Increased Liquidity for the Informal Sector
Small-scale merchants, farm producers, haulers, craftsmen, and market participants relying significantly on cash will experience ease in transferring money, purchasing stock, and expanding their businesses.
2. Reduced Transaction Friction
Companies that once faced limiting restrictions now recover agility, enhancing business continuity and lowering administrative challenges.
3. Restoration of Public Trust
After the trauma of the cash scarcity era, easing restrictions may slowly rebuild confidence in the banking system and encourage more people to save and transact through formal channels.
4. Policy Simplicity
The updated limits, while still restricted, are more straightforward and less administrative compared to the special-authorization system.
The Disadvantages: Policy Volatility, Inflationary Risks, and Stunted Digitalisation
Nonetheless, the policy change is also accompanied by drawbacks:
1. Weakening of Monetary Policy Credibility
Regular significant reversals indicate instability and undermine confidence. A central bank needs to be consistent and foreseeable; Nigeria’s policy environment has shifted in the contrary.
2. Potential for More Money Laundering
Unlimited cash deposits and increased withdrawal limits are inconsistent with standards for preventing illegal financial transactions.
3. Undermining Digital Payment Growth
The increase in fintech was expedited amidst cash availability. A return to reliance on cash might hinder innovation. Dampen the use of safer trackable digital methods.
4. Increased Risk of Robbery and Cash-Based Crime
An increased amount of cash in use results in tangible currency to be stolen additional opportunities for criminals and amplified operational difficulties for the police.
5. Higher Costs of Cash Management
The processes of currency production, circulation, and safeguarding place financial strains on the banking sector and the CBN.
Policy Details and Operational Complexities
The CBN’s circular offers instructions for operations:
– Excess withdrawal charges:
3 percent for individuals
5 percent for corporates
– Revenue sharing:
40 percent to CBN, 60 percent to banks
– Withdrawals from ATMs and PoS terminals contribute to the limit, highlighting the importance for customers to monitor where their withdrawals originate.
– ATMs can now be loaded with all denominations, although third-party cheque cashing is still limited to N100,000.
– Exemptions are maintained for government revenue accounts, microfinance banks, and primary mortgage banks.
– The removal of exemptions for embassies and donor agencies is a move that some parties consider diplomatically risky.
The CBN frames this policy change as a balance, boosting liquidity while still maintaining the nation’s goal of a cashless economy. Nevertheless, its effectiveness depends on the ability of the government and financial institutions to encourage payments while addressing the security challenges posed by greater cash circulation.
A Relief Today, a Question Mark Tomorrow
The CBN’s updated cash-policy structure provides support for families, small enterprises, and the informal sector. It addresses some of the severe effects of previous policies and shows a readiness, though delayed, to adjust to practical realities.
However, the enduring consequences are complex. The policy creates openings, as money laundering hampers progress in payments, increases security threats, and shows a regulatory environment grappling with achieving stability and trustworthiness.
Nigeria is at an intersection. While cash can relieve hardships, it cannot shape the future economic landscape. The current task is to apply this policy without hindering progress, undermining financial integrity, or jeopardizing monetary stability.
The question of whether this constitutes a liberalisation or an expensive withdrawal will in the end hinge on a single element, the CBN’s ability to pair increased liquidity with stronger oversight, steadfast policy direction, and sustained digital-payment incentives.
Only then can Nigeria avoid sliding backward and instead build a financial system that truly reflects the realities of its people, its economy, and its future.
Blaise, a journalist and PR professional, writes from Lagos, can be reached via: blaise.udunze@gmail.com










You must be logged in to post a comment Login