Economy
Systemically Weak Banks Put Nigeria’s $1Trillion Ambition at Risk -By Blaise Udunze
Otherwise, the uncomfortable truth will persist; one well-capitalised bank elsewhere will continue to stand taller than an entire banking system at home. Whilst a $1 trillion economy cannot be built on a weak banking system. The sooner this reality is acknowledged, the better Nigeria’s chances of turning ambition into achievement.

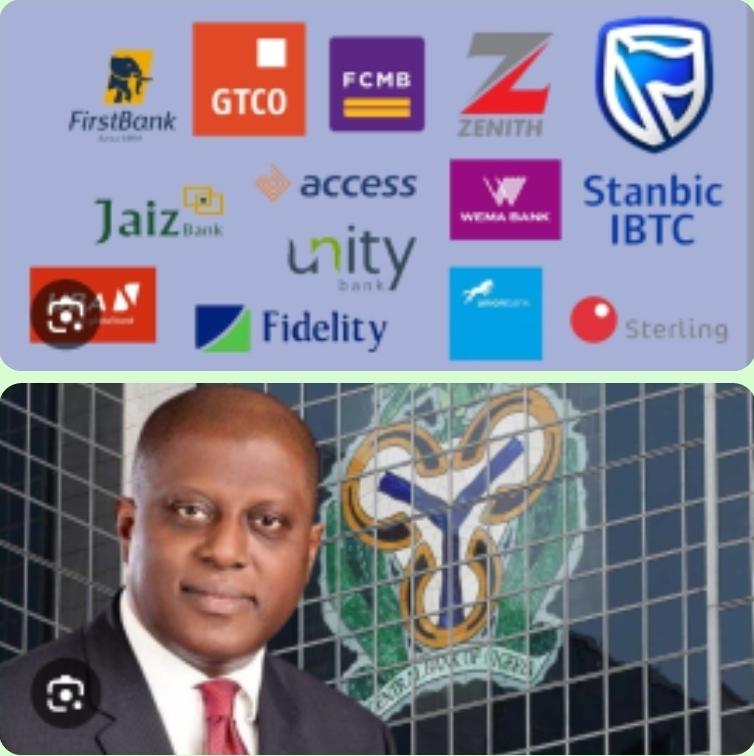
Nigeria’s banking sector has just undergone one of its most ambitious recapitalisation exercises in two decades, all thanks to the Central Bank of Nigeria under the leadership of Olayemi Cardoso. About N4.65 trillion ($3.38) has been raised. Balance sheets have been strengthened, at least the improvement could be said to exist in reports or accounting figures. Regulators have drawn a new line in the sand, proposing N500 billion for international banks, N200 billion for national banks, and N50 billion for regional players. This is a bold reset.
Meanwhile, as the dust settles, an uncomfortable question refuses to go away, which has been in the minds of many asking, “Has Nigeria once again solved yesterday’s problem, while tomorrow’s risks gather quietly ahead?”
At a period when banks globally are being tested against tougher buffers, cross-border shocks, and higher regulatory expectations, Nigeria’s revised benchmarks risk falling short of what the global system demands.
In a world where scale, resilience, and competitiveness define banking credibility, capital is not measured in isolation; it is judged relative to peers, risks, and ambition.
Because when placed side by side with a far more unsettling reality, that a single South African bank, Standard Bank Group, rivals or even exceeds the valuation and asset strength of Nigeria’s entire banking sector, the celebration begins to feel premature.
The recapitalisation may be necessary. But is it sufficient? The numbers are not just striking, they are deeply revealing. Standard Bank Group, with a market valuation hovering around $21-22 billion and assets approaching $190 billion, stands as a continental giant. In contrast, the combined market capitalisation of Nigeria’s listed banks, even after recent capital raises, struggles to match that scale.
The combined value of the 13 listed Nigerian banks reached N16.14 trillion (11.9 billion) using N1.367/$1 in early April 2026, following the recapitalization momentum.
Even more revealing is the contrast at the top. Zenith Bank is valued at N4.7 trillion ($3.44 billion), Guaranty Trust Holding Company, widely admired for efficiency and profitability, is valued at under N4.6 trillion ($3.37 billion), while Access Holdings, despite managing tens of billions in assets, carries a market value below the upper Tier’s N1.4 trillion ($1.02 billion).
This is not merely a gap. It is a structural disconnect. And it raises a critical point, revealing that recapitalisation is not just about meeting regulatory thresholds; it is about closing credibility gaps.
With accounting figures or reports, Nigeria’s new capital thresholds appear formidable. But paper strength is not the same as real strength.
The naira’s persistent depreciation has quietly undermined the meaning of these figures. What looks like N500 billion in nominal terms translates into a much smaller and shrinking figure in dollar terms.
This is the misapprehension at the heart of Nigeria’s banking reform, as we are measuring financial strength in a currency that has been losing strength.
In real terms, some Nigerian banks today may not be significantly stronger than they were years ago, despite meeting much higher nominal thresholds. So while regulators see progress, global investors see vulnerability. Markets are rarely sentimental. They price risk with ruthless clarity.
The valuation gap between Nigerian banks and their South African counterparts is not an accident; it must be made known that it is strategic intentionality. By this, it truly reflects a deeper judgment about currency stability, regulatory predictability, governance standards, and long-term growth prospects. Investors are not just asking how much capital Nigerian banks have. They are asking how durable that capital is.
Even when Nigerian banks post strong profits, much of it has been driven by foreign exchange revaluation gains rather than core lending or operational efficiency. The CBN’s decision to restrict dividend payments from such gains is telling; it acknowledges that not all profits are created equal. True strength lies not in accounting gains, but in economic impact.
Nigeria has travelled this road before. Under Charles Soludo, the 2004-2006 banking consolidation raised minimum capital from N2 billion to N25 billion, reducing the number of banks dramatically and producing industry champions like Zenith Bank and United Bank for Africa. For a time, Nigerian banks expanded across Africa and became formidable competitors.
But the momentum did not last, emanating with lots of economic headwinds. One amongst all that played out was that the global financial crisis exposed weaknesses in governance and risk management, leading to another wave of reforms under Sanusi Lamido Sanusi. The lesson from that era remains clear, which revealed that capital reforms can stabilise a system, but they do not automatically transform it. Without bigger structural changes, the gains fade.
The real weakness of Nigeria’s current approach is not the size of the thresholds; it is their rigidity. Fixed capital requirements do not adjust for inflation, reflect currency depreciation, scale with systemic risk, or capture the complexity of modern banking.
In contrast, global regulatory frameworks are increasingly dynamic and risk-based. This is where Nigeria risks falling behind again. Because while the numbers have changed, the philosophy has not.
Nigeria’s economic aspirations are bold. The country speaks confidently about building a $1 trillion economy, expanding infrastructure, and driving industrialization, but in dollar terms, many Nigerian banks remain small, too small for the scale of ambition the country now proclaims. Albeit, it must be understood that ambition alone does not finance growth. Banks do.
And here lies the uncomfortable mismatch, which is contradictory in nature because the economy Nigeria wants to build is significantly larger than the banks it currently has.
In South Africa, what Nigerian stakeholders are yet to understand is that large, well-capitalised banks play a central role in financing infrastructure, corporate expansion, and consumer credit. Their scale allows them to absorb risk and deploy capital at levels Nigerian banks struggle to match. Without comparable financial depth, Nigeria’s development ambitions risk being constrained by its own banking system.
At its core, banking is about channeling capital into productive sectors, as this stands as one of its responsibilities if it truly wants to ever catch up to a $1 trillion economy. Yet Nigerian banks have increasingly, in their usual ways, leaned toward safer, short-term returns, particularly government securities. This is not irrational. It is a response to high credit risk, regulatory uncertainty, and macroeconomic instability.
But it comes at a cost. Yes! The fact is that when banks prioritise safety over lending, the real economy suffers. What this tells us is that manufacturing, agriculture, and small businesses remain underfunded, limiting growth and job creation.
Recapitalisation is meant to change this dynamic. Stronger capital buffers should enable banks to take on more risk and finance larger projects. But capital alone will not solve the problem. Confidence will.
One of the most persistent obstacles facing Nigerian banks is currency volatility. Each major devaluation of the naira erodes investor returns and reduces the dollar value of bank capital. This creates a contradiction whereby banks appear profitable in naira terms, but unattractive in global markets.
In contrast, South Africa benefits from a more stable currency environment and deeper capital markets. Without much ado, it is clear that this stability attracts long-term institutional investors that Nigeria struggles to retain. Until this macroeconomic challenge is addressed, recapitalisation alone cannot close the gap because without making it a priority, even the strongest banks will remain constrained.
In a global competitive financial market, one would agree that capital is necessary, but not sufficient. Beyond the capital, one crucial lesson stakeholders in Nigeria’s banking space must understand is that investors’ confidence is heavily influenced by governance standards and operational efficiency, which mainly guarantee more success and capability. Also, another relevant trait to sustainable banking is transparency, regulatory consistency, and accountability, which matter as much as balance sheet strength.
While Nigerian banks have made progress, lingering concerns remain around insider lending, regulatory unpredictability, and complex ownership structures. If policymakers revisit and reflect on the episodes involving institutions like First Bank of Nigeria and the liquidation of Heritage Bank, this will reinforce the perceptions of systemic risk.
Recapitalisation offers an opportunity to reset governance standards, but only if it is accompanied by stricter enforcement and greater transparency, with the key stakeholders seeing beyond the capital growth.
As if traditional challenges were not enough, Nigerian banks are also facing increasing competition from fintech companies. Nigeria has emerged as a leading fintech hub in Africa, reshaping payments, lending, and digital banking.
To remain relevant, banks must invest heavily in technology, an area that requires not just capital, but smart capital, ensuring that digital innovation becomes a core strength rather than an external add-on. The recapitalisation exercise provides the financial capacity. Whether banks use it effectively is another matter entirely.
So, are Nigeria’s new capital thresholds already outdated? Not yet. But they are already under pressure, pressure from inflation, currency weakness, global competition, and Nigeria’s own economic ambitions.
The truth is that the reforms are a step in the right direction, but they may already be systemically weak in the face of global realities. Whilst the actors keep focusing heavily on capital thresholds without addressing deeper structural issues, the reforms risk creating a system that is compliant, but not competitive, stable but not strong.
The recapitalisation exercise has bought Nigeria time. That is its greatest achievement. But time is only valuable if it is used wisely.
If policymakers treat this reform as a destination, the thresholds will age faster than expected. If they treat it as a foundation, Nigeria has a chance to build a banking system capable of supporting its ambitions.
It can either strengthen its financial foundations to match its economic ambitions or continue to pursue growth on a fragile base.
The warning signs are already visible. Systemic weaknesses, if left unaddressed, will not remain contained; they will surface at the worst possible moment, undermining confidence and limiting progress.
Otherwise, the uncomfortable truth will persist; one well-capitalised bank elsewhere will continue to stand taller than an entire banking system at home. Whilst a $1 trillion economy cannot be built on a weak banking system. The sooner this reality is acknowledged, the better Nigeria’s chances of turning ambition into achievement.
Blaise, a journalist and PR professional, writes from Lagos and can be reached via: blaise.udunze@gmail.com













You must be logged in to post a comment Login