Africa
How Nigeria’s New Tax Law Could Redefine Risk in the Banking Sector -By Blaise Udunze
For the policy to succeed without damaging the banking system, regulators must ensure clear thresholds and exemptions, strong data protection guarantees, phased implementation and ensure sustained public education to redirect hostility away from banks.

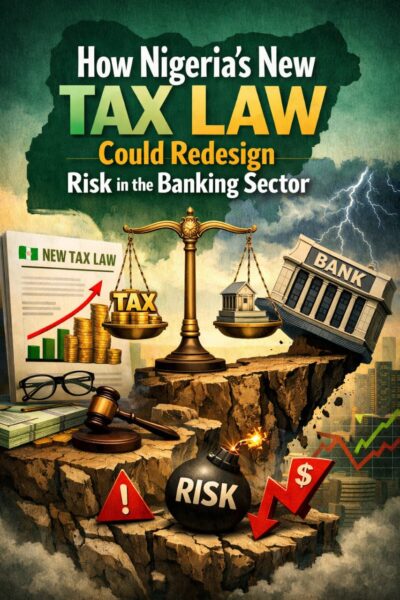
Nigeria’s new tax identification portal goes live nationwide tomorrow, Monday, January 1, 2026, marking a pivotal moment in the country’s fiscal and financial governance. Designed to modernise tax administration and strengthen taxpayer identification, the reform reflects a decisive shift in economic strategy by a government grappling with shrinking oil revenues, rising public debt, and widening fiscal deficits.
At the centre of this shift is a deeper integration of identity systems, banking data, and tax administration, most notably the adoption of the National Identification Number (NIN) as a tax identification mechanism for operating bank accounts. In parallel, banks will also begin charging a N50 stamp duty on electronic transfers of N10,000 and above, following the implementation of the Tax Act.
Individually, these measures may appear modest, even reasonable. Collectively, however, they signal a fundamental reordering of the relationship between the state, banks, and citizens with far-reaching implications for banking business, customer trust, financial inclusion, and credit creation.
Banks at the Centre of Fiscal Enforcement
Under the new tax framework, Nigerian banks are no longer merely financial intermediaries or corporate taxpayers. They are increasingly positioned as collection agents, reporting hubs, and frontline enforcement points for government revenue policy.
The linkage of NIN to tax compliance, combined with transaction-based stamp duties, reinforces a stark reality that the banking system has become the most visible and accessible channel through which the state now extracts revenue from citizens.
This expanded role exposes banks to a new layer of risk not just financial or operational, but social, reputational, and political risks that extend far beyond balance sheets.
A Structural Shift in the Banking, Tax Relationship
Historically, banks played a facilitative role in tax compliance, primarily through payment processing and remittance support. The use of NIN as a tax identifier marks a structural departure from this model.
Bank accounts are no longer merely financial tools; they are becoming gateways to tax visibility.
This shift fundamentally alters the risk profile of the banking business. Banks are now exposed not only to credit, market, and operational risks, but also to heightened social backlash, reputational damage, and political sensitivity, arising from their expanded enforcement role.
Account Friction and Slower Customer Onboarding
One of the earliest and most visible consequences of NIN-based tax identification is increased friction in account opening and maintenance.
Consequently, in a real sense, millions of Nigerians will continue to face challenges with the NIN system, including delays in enrolment and correction, biometric mismatches as well as inconsistencies between NIN, BVN, and bank records.
For banks, this translates into slower onboarding processes, higher rates of account restriction or rejection, and increased congestion across branches and digital platforms.
What should be a growth engine for deposit mobilisation instead becomes a bottleneck, resulting in lost customers, fewer transactions, and weakened scale advantages in an increasingly competitive banking environment.
Banks as the Face of an Unpopular Tax Regime
Perhaps the most underappreciated consequence of the new tax regime is the escalation of customer hostility toward banks.
When accounts are flagged, restricted, or subjected to enhanced scrutiny, customers rarely direct their frustration at tax authorities or policymakers. Instead, they confront the most visible institution in the chain, their bank.
Banks are increasingly blamed for account freezes, accused of colluding with government, and perceived as punitive rather than service-oriented institutions. This hostility is particularly pronounced among informal sector operators, small traders, artisans, and self-employed professionals with irregular income streams.
In a low-trust economy such as Nigeria’s, perception often outweighs regulation. Banks risk becoming the public face of coercive taxation, absorbing reputational damage for policies they neither designed nor control.
Erosion of Trust in the Banking Relationship
Banking fundamentally depends on trust that deposits are safe, transactions are private, and institutions act in customers’ best interests.
When NIN becomes a tax enforcement gateway, that trust begins to fray. Banks are no longer seen primarily as custodians of savings, enablers of enterprise, or neutral financial intermediaries. Instead, they are increasingly perceived as extensions of tax authorities, surveillance nodes, and compliance police.
Once trust erodes, customer behaviour adjust often in ways that undermine the formal financial system itself.
The Hidden Impact of the N50 Stamp Duty
The introduction of a N50 stamp duty on electronic transfers of N10,000 and above may appear trivial. In practice, it carries outsized implications.
For many Nigerians, especially low- and middle-income earners, electronic transfers are not discretionary transactions. They are salary payments, family support remittances, SME operating expenses, and routine commercial settlements.
Customers rarely distinguish between government levies and bank charges. The stamp duty will therefore be perceived as yet another bank fee, deepening resentment toward institutions already accused of excessive charges.
Behaviourally, customers may respond by breaking transactions into smaller amounts, increasing cash usage, or migrating to informal transfer channels, distorting transaction patterns and weakening the efficiency of the digital payments ecosystem.
Although banks merely collect the duty on behalf of the government, they will once again bear the reputational cost.
Threat to Deposit Mobilisation and Liquidity
Fear of tax exposure is a powerful behavioural driver. As NIN becomes closely associated with tax scrutiny and transaction charges mount, many customers are likely to reduce account balances, avoid lump-sum deposits, split transactions to stay below thresholds, or move funds outside the banking system entirely.
For banks, the consequences are clear, as these will result in slower deposit growth, volatile liquidity positions, and reduced capacity to fund loans.
Deposit mobilisation is the lifeblood of banking. Any policy that discourages formal savings weakens banks’ intermediation role and, by extension, the broader economy.
Reversal of Financial Inclusion Gains
Nigeria has invested more than a decade in expanding financial inclusion through agent banking, digital wallets, and tiered KYC frameworks. The use of NIN as a tax trigger threatens to reverse these gains.
Many newly banked individuals, particularly those at the base of the economic pyramid, may abandon formal accounts, revert to cash-based transactions, or rely on informal savings mechanisms.
The irony is stark as an identifier designed to formalise the economy may inadvertently push activity back into informality.
Rising Compliance, Legal, and Technology Costs
Operationally, integrating NIN as a tax identifier significantly increases banks’ compliance burden. However, institutions are expected to synchronise multiple databases, resolve inconsistencies at scale, implement continuous monitoring systems while also managing customer disputes arising from mismatches or wrongful flags.
The challenges inherent in these demands require heavy investment in IT infrastructure, expanded compliance teams and enhanced cybersecurity. The costs either erode profitability or are passed on to customers, further fuelling public resentment.
Credit Creation and Economic Growth at Risk
Reduced deposits, higher compliance costs, reputational strain, and customer attrition converge on a single outcome that mainly constrained lending capacity.
There is no two ways about this, banks under sustained pressure will tighten credit standards, reduce SME and consumer lending, and favour low-risk government securities. The ripple effects include slower job creation, constrained entrepreneurship, and, on a dangerous level, it leads to weaker economic growth, ultimately undermining the very revenue base the tax reform seeks to expand.
Revenue Without Ruin
No doubt, linking NIN to tax identification and expanding transaction-based levies may enhance government visibility over economic activity, but in reality they carry significant unintended consequences for banking business.
They risk weakening customer trust, undermining deposit mobilisation, reversing financial inclusion gains, increasing operational and reputational risks, and constraining credit growth.
Banks do not oppose taxation. What they caution against is turning financial inclusion infrastructure into a blunt instrument of tax enforcement without adequate safeguards.
For the policy to succeed without damaging the banking system, regulators must ensure clear thresholds and exemptions, strong data protection guarantees, phased implementation and ensure sustained public education to redirect hostility away from banks.
Ultimately, the critical question is not legislative readiness but execution, especially coordination across institutions, technological preparedness and the capacity to prevent unintended disruption to businesses and citizens alike. The authorities must understand that when revenue meets risk, wisdom lies in balance.
Blaise, a journalist and PR professional, writes from Lagos and can be reached via: blaise.udunze@gmail.com










You must be logged in to post a comment Login