Africa
A Guide to Mortgage Options in Nigeria –By Kator Ifyalem
For most Nigerians, the FMBN and PMBs offer the most affordable mortgage options, especially for salaried workers. Commercial banks provide faster processing but at higher costs. Developer financing and cooperative societies offer alternative routes for those outside the formal sector. Always compare options, prepare your documents, and seek professional advice before committing.

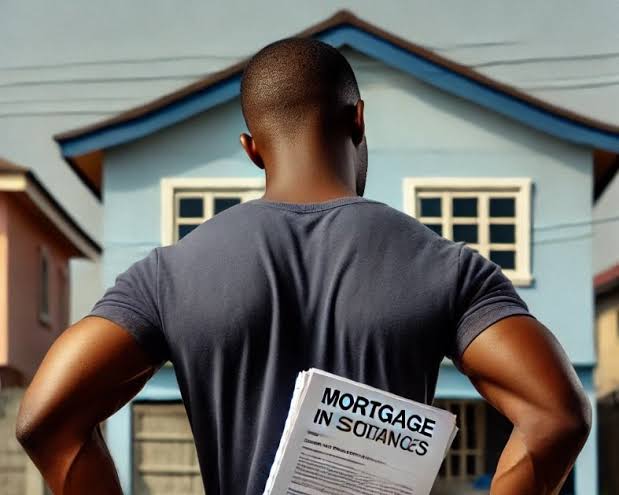
Nigeria’s property market is vast and dynamic, characterized by a significant housing deficit of about 28 million homes. For most Nigerians, buying property outright is financially out of reach, making mortgage financing a critical tool for homeownership. However, the mortgage sector is still underdeveloped, with less than 1% of GDP currently financed through mortgages. High interest rates, stringent eligibility criteria, and complex application processes remain persistent challenges, especially for self-employed and informal sector workers.
The Federal Mortgage Bank of Nigeria (FMBN): The FMBN is the government’s primary vehicle for affordable housing finance. Its flagship product, the National Housing Fund (NHF) scheme, is open to Nigerian workers who contribute to the fund. The NHF offers loans up to ₦15 million, with interest rates typically lower than commercial banks (often single-digit), and repayment periods of up to 25 years. The FMBN also provides Estate Development Loans, Home Renovation Loans, Rent-to-Own schemes, and Diaspora NHF Mortgages. While FMBN loans are more accessible and affordable, they face issues like slow processing, bureaucratic delays, and limited reach to informal sector workers. Despite these limitations, the FMBN remains a top choice for salaried workers seeking low-interest mortgages.
Commercial Bank Mortgage Options: Major commercial banks such as Access Bank, First Bank, UBA, Stanbic IBTC, and Zenith Bank offer mortgage products. These loans generally feature higher interest rates (often 20–25%), shorter repayment periods (typically 5–10 years), and require substantial down payments (20–30%). Documentation requirements include proof of income, bank statements, and property valuation reports.
Commercial bank mortgages offer notable advantages including faster processing times and a wider range of property choices. However, these benefits come with significant drawbacks, they typically charge higher interest rates and fees that increase the overall cost of homeownership, while also imposing stricter eligibility criteria that are particularly challenging for informal sector workers.
Primary Mortgage Banks (PMBs): Nigeria has about 32 primary mortgage banks, including Abbey Mortgage Bank, FirstTrust Mortgage Bank, and Platinum Mortgage Bank. These institutions offer products tailored to various income levels, with equity contributions ranging from 20% to 30% and repayment periods of up to 25 years. PMBs often provide more flexible terms than commercial banks and may offer joint mortgages for partners or family members.
While offering flexible repayment options and lower equity requirements for certain products, they have limited branch networks which may present accessibility challenges for some customers, and its approval processes tend to be slower compared to traditional commercial banks.
Developer Financing and Rent-to-Own Schemes: Many property developers offer in-house financing or rent-to-own schemes, allowing buyers to move in immediately and pay in installments over several years. These arrangements can be more accessible for buyers with irregular income or limited savings. However, they often come with higher overall costs and less legal protection than traditional mortgages.
Government Housing Initiatives: Recent government efforts include a ₦1 trillion ($654 million) housing fund, partly financed by a 40-year World Bank loan at 1% interest, matched by private sector contributions. This fund aims to provide affordable mortgages at single digit or low double digit interest rates for up to 25 years, with the goal of stimulating a construction boom and increasing home ownership rates. State governments and public private partnerships are also launching targeted housing programs, especially in urban centers.
Cooperative Societies and Savings Schemes: Cooperative societies play a significant role in property financing, particularly for low- and middle-income earners. Members pool resources to purchase land or build homes, often benefiting from group discounts and flexible payment plans. Joining or forming a housing cooperative is an effective way to access property without traditional mortgage requirements.
International or Diaspora Mortgage Options: Nigerians in the diaspora can access the FMBN’s Diaspora NHF Mortgage, which allows them to buy property in Nigeria using foreign currency. Legal considerations include compliance with Nigerian property laws and foreign exchange regulations.
Step-by-Step Guide to Securing the Most Affordable Mortgage
Initial Steps and Financial Preparation – Assess your financial situation and creditworthiness. Also, save for a down payment (ideally 20–30% of property value).
Document Checklist – Proof of income (such as payslips or tax returns), bank statements, a valid form of identification, evidence of your NHF contributions (specifically required for FMBN applications), and property valuation reports for the real estate in question.
Timeline Expectations – Processing time for FMBN is between 6 to 12 months, while commercial banks lasts from 1 to 3 months. PMBs require a duration of 2 to 6 months for processing applications.
Cost-Saving Strategies – Compare interest rates and fees across multiple lenders, as even small percentage differences can significantly impact the total amount repaid over time. Opting for longer repayment periods can help reduce your monthly payment obligations, creating more breathing room in your budget, though be aware this may increase total interest paid over the life of the loan. Additionally, consider exploring government-backed loan programs which typically offer lower interest rates and more favorable terms than conventional financing options, potentially saving you thousands over the course of your loan term.
Common Pitfalls to Avoid: It is crucial to request a full breakdown of costs before signing any agreement to avoid hidden fees and charges. Always ensure property titles are clear and verified by a legal professional to prevent legal issues down the road. Conducting due diligence by working only with licensed lenders and real estate professionals can protect your investment. Should you encounter any fraudulent practices during the process, don’t hesitate to report them to the appropriate regulatory authorities for consumer protection.
For most Nigerians, the FMBN and PMBs offer the most affordable mortgage options, especially for salaried workers. Commercial banks provide faster processing but at higher costs. Developer financing and cooperative societies offer alternative routes for those outside the formal sector. Always compare options, prepare your documents, and seek professional advice before committing.
Key Contacts:
~ Federal Mortgage Bank of Nigeria: [www.fmbn.gov.ng](https://www.fmbn.gov.ng)
~ Abbey Mortgage Bank, FirstTrust Mortgage Bank, Platinum Mortgage Bank (see their official websites)
~ Leading commercial banks: Access Bank, First Bank, UBA, Stanbic IBTC, Zenith Bank.













You must be logged in to post a comment Login